 EN
 PT_BR
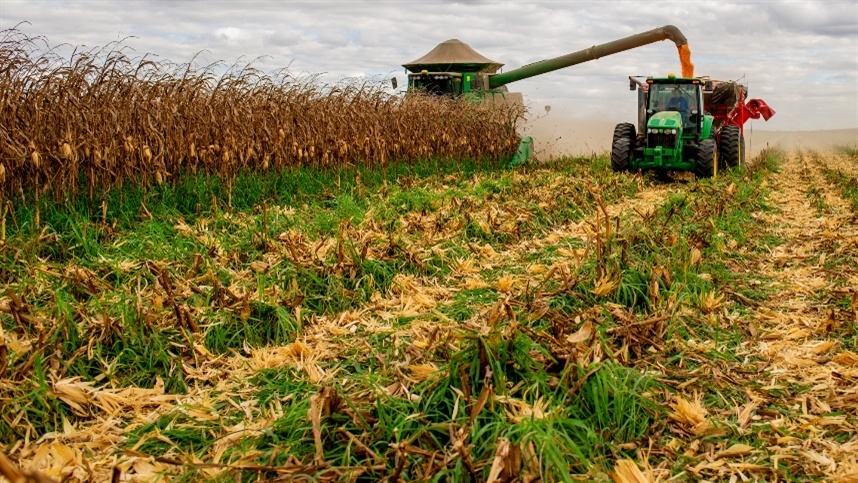
The market of corn In the South and Midwest, the situation remains marked by sporadic negotiations, cautious buyers, and more selective producers, while the progress of the new harvest shares attention with climatic effects and regional differences in supply. According to an analysis by TF Agroeconômica, the scenario combines reduced liquidity, demand concentrated on restocking, and distinct planting paces among the main producing states.
In Rio Grande do Sul, prices range between R$ 60.00 and R$ 61.98 per sack, while the average state price increased by 0.62%, to R$ 61.98. Planting for the 2026/27 crop has reached 60% of the planned area and is practically complete in the Northwest. Frosts caused damage to crops planted earlier and required replanting in specific areas, in addition to localized losses caused by hail.
In Santa Catarina, prices are close to R$ 60.00 per sack, while demand is around R$ 55.00. The state consumes approximately 8.5 million tons per year and produced 2.67 million tons in the 2025/26 harvest, maintaining a deficit of close to 6 million tons and dependence on corn from other regions and Paraguay.
In Paraná, purchases are also around R$60.00 per sack, while demand is around R$55.00 CIF. The harvest of the second crop of 2025/26 reached 95% of the 2.91 million hectares, and the planting of the first crop of 2026/27 reached 43% of the projected 373,000 hectares. Of the planted areas, 97% are in good condition.
In Mato Grosso do Sul, prices range from R$$ 54.00 to R$$ 55.50 per sack. After a series of increases, prices have stabilized and declined, while the bioenergy industry continues to absorb part of the available supply.